SPDR S&P 500 ETF (SPY)
Update 3/31/2017: SPY rose continually after I entered the position. I exited with 21 days before expiration and with the profit at 6% of its maximum potential. Further upward movement will make the position unprofitable.
My goal was 25% of the maximum, but I decided to eliminate the risk of a loss for two reasons.
First, the spread I constructed had quite a narrow profit zone. That’s what the options grid allowed. In retrospect, it might have been better to have simply passed on the trade.
Second, the Elliott wave analysis of short-term movements presents an uncertain view of the future. I count the price as having being in an A wave upward retracement of a 3rd wave to the downside within a higher-level downward movement that began on March 1. The upward thrust has retraced a Fibonoacci 61.8% of the 3rd wave, reaching a common reversal point.
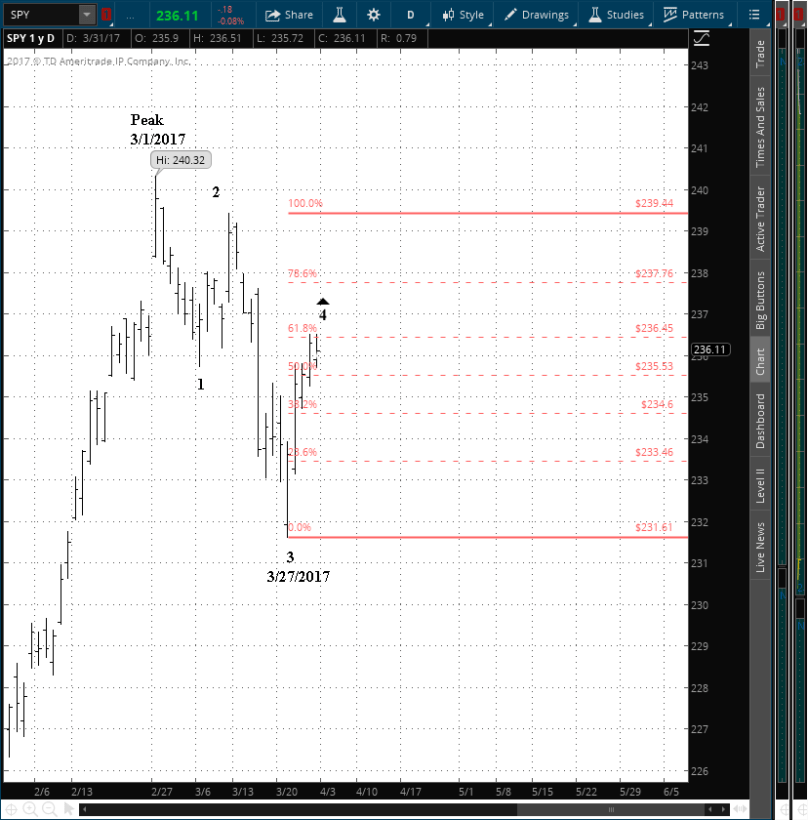
Fibonacci retracements come with no guarantees. Moreover, a 4th wave like as not will take a sideways form, such as a Flat. Rather than risk the loss, it made more sense to me to take what profits I could and come back another day with a structure more likely to succeed.
Shares rose by 1.2% over seven days, or a +64% annual rate. The options position produced a 6.4% yield on debit for a +336% annual rate.
SPY’s implied volatility has risen to a relatively high level within a very narrow range.
I shall use the apr series of options, which trades for the last time 28 days hence, on April 21.
Implied volatility stands at 13% and, by definition, is nearly identical with the VIX, a measure of the volatility of the S&P 500 index.
SPY’s IV stands in the 21st percentile of its annual range and the 79th percentile of its most recent broad movement.


You must be logged in to post a comment.